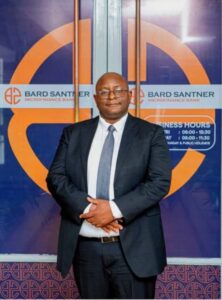
HARARE -The Reserve Bank of Zimbabwe (RBZ) has licensed Bard Santner Microfinance Bank Limited as a deposit-taking microfinance institution with effect from 1 October 2026.
In a public notice issued in terms of the Microfinance Act [Chapter 24:30] as read with section 5 of the Microfinance (General) Regulations, 2025 (SI 85 of 2025), the central bank announced the registration of the Harare-based Bard Santner Inc group subsidiary.
Bard Santner Microfinance Bank (BSMB) said the licence is the foundation for its longer-term banking ambitions and will anchor a diaspora banking and investment platform designed to serve Zimbabweans and other Africans living across the continent and worldwide. The group has offices in Harare, Johannesburg and New York.
The licence authorises 15 activities including receiving savings deposits, extending consumer, mortgage and commercial credit, factoring, forfaiting, bank guarantees, export and import facilitation subject to the Exchange Control Act [Chapter 22:05], structured finance, buying and selling financial instruments, money transmission services, foreign currency trading subject to exchange control, issuing and administering means of payment including credit cards, travellers cheques and bankers’ drafts, money broking, safekeeping and administration of valuables, portfolio management and advisory services, financial leasing, hire-purchase and credit reference services.
The bank said it will provide the full suite with emphasis on diaspora remittances, building on its subsidiary TX Money Transfer. It will operate as a cross-border financial connector built around real-time payments and banking architecture purpose-built for diaspora flows and SME trade.
Zimbabwe’s diaspora remittances reached US$2.45 billion in 2025, up 14 percent on the prior year and about 16.1 percent of total foreign currency earnings. Formal remittances reached US$1.62 billion in the first seven months of 2026, up 24 percent on the same period in 2025, according to the RBZ. African diaspora remittances reached an estimated US$124.2 billion in 2025, surpassing foreign direct investment and official development assistance.
BSMB Managing Director Ngonidzashe Chikowore said remittances have been treated as cash for consumption rather than capital for investment.
“This is not the launch of just another start-up bank. Zimbabwe and Africa do not need another bank for the sake of a bank,” Chikowore said. “What our people need — at home and abroad — is an institution, no matter how small to start with, that meets them where they live, earn, transact and aspire.”
Chikowore said the bank’s model is digital-first, prioritising agility and utility over scale, with products designed around life events, 24/7 availability and AI-driven insights.
“A nurse in Manchester, UK, or a doctor in Melbourne, Australia, a restaurant worker in Johannesburg, South Africa, should be able to send money home or fund a business in Harare or Bulawayo as easily as he or she pays an electricity bill electronically, order an Uber or pizza digitally,” he said.
Bard Santner Group Chief Executive Senziwani Sikhosana said the licence is a transformative moment for Zimbabweans and other global citizens who call more than one country home.
“We will not just be moving money; we are bridging people and economies. This licence allows us to build a trusted foundation where the diaspora can save, invest, and grow their wealth securely, directly contributing to individual, organisational and national economic development of their home countries in a structured and sustainable way,” Sikhosana said.
As a deposit-taking microfinance bank, BSMB falls within the regulated deposit-taking framework, subject to capital adequacy standards, governance requirements and ongoing supervisory oversight by the RBZ. The bank said its rollout will be phased, with full banking operations expected to commence soon.
“The licence is not merely a vote of confidence in Bard Santner, but also a responsibility. Durable institutions are not built on speed alone. They are built on capital, corporate governance and trust,” Chikowore said.
Bard Santner said its model draws lessons from thriving banking fintechs like GoTyme Bank and Bank Zero in South Africa, which boasts the continent’s most developed fintech ecosystem, accounting for 40 percent of Africa’s fintech market revenue.